Leaving substantial cash balances in a traditional checking or brick-and-mortar savings account yielding 0.01% APY guarantees a steady loss of purchasing power to inflation. Online High-Yield Savings Accounts (HYSAs) offer a risk-free method to earn competitive yields on emergency reserves, sinking funds, and short-term capital.
Because online institutions operate without costly branch networks, they pass operational savings directly to depositors through elevated interest rates. In this guide, we break down how APY calculations work, the mechanics of FDIC deposit insurance, taxation rules on earned interest, and how to select the best account for your liquidity needs.
How HYSAs Work: The Economics of Digital Banking
Traditional retail banks maintain extensive physical branch networks, teller staff, and real estate leases. Online banks, by contrast, operate digital-first infrastructure with lower cost-to-income ratios, allowing them to offer Annual Percentage Yields (APY) that are 10x to 12x higher than legacy institutions.
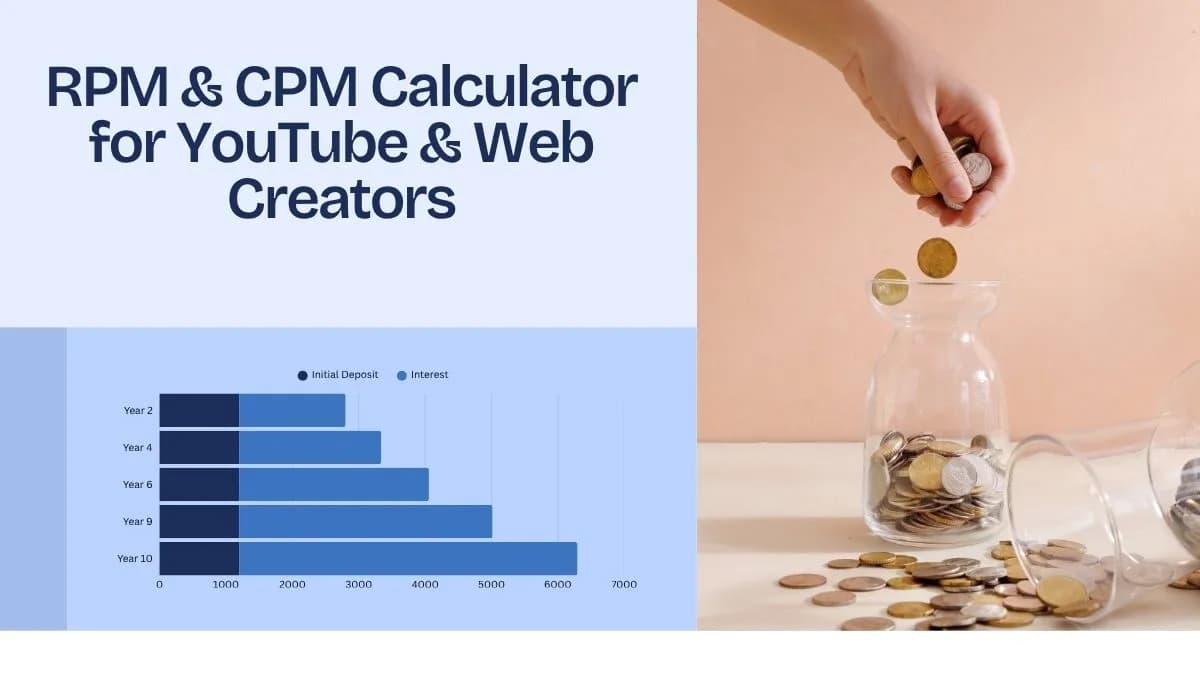
Interest Compounding Formula: A = P(1 + r/n)^(nt)
Where A = Final Balance, P = Principal, r = Nominal Rate, n = Compounding Periods/Year, t = Years.
Most top-tier HYSAs compound interest daily and credit it to your account monthly, maximizing the compounding velocity of your capital.
FDIC and NCUA Insurance Limits: Protecting Your Principal
The single most critical safety feature of a legitimate HYSA is federal deposit insurance backed by the full faith and credit of the United States government:
Taxes on HYSA Interest: IRS Form 1099-INT
Interest earned from a High-Yield Savings Account is considered ordinary taxable income by the IRS. If your account generates $10 or more in interest during a calendar year, your financial institution will issue an IRS Form 1099-INT.
Unlike long-term capital gains, bank interest is taxed at your marginal federal income tax bracket plus applicable state and local income taxes. Factor these taxes into your net yield calculations when planning large multi-year savings goals.
HYSA vs. Traditional Bank Accounts: Comparison
| Feature |
High-Yield Savings Account |
Traditional Brick-and-Mortar Savings |
| Typical APY Range |
4.00% – 5.25% APY |
0.01% – 0.05% APY |
| Monthly Maintenance Fees |
$0 (Almost universally waived) |
$5 – $15/month unless balance thresholds met |
| Deposit Insurance |
FDIC/NCUA insured to $250k |
FDIC/NCUA insured to $250k |
| Liquidity Speed |
1–2 business days via ACH transfer |
Instant physical branch cash withdrawal |
How to Choose the Best HYSA for Your Goals
- Verify FDIC/NCUA Status: Confirm bank registration using the official FDIC BankFind tool.
- Check for Hidden Fees: Ensure zero monthly maintenance fees and no minimum balance penalties.
- Evaluate Transfer Limits: Verify ACH withdrawal transfer speed and monthly limits.
- Mobile App Experience: Look for seamless mobile check deposit and automated recurring transfers.
Explore our comprehensive guides on Savings Goals & Budgeting, Emergency Funds, and Compound Interest Calculators.